
Important security note: Warning of attempted fraud in the name of DWS
We have detected that fraudulent individuals are misusing the "DWS" trademark and the names of DWS employees on the internet and social media. These fraudsters are operating fake websites, Facebook pages, WhatsApp groups and Mobile Apps. Please be aware that DWS does not have any Facebook Ambassador profiles or WhatsApp chats. If you receive any unexpected calls, messages, or emails claiming to be from DWS, exercise caution and do not make any payments or disclose personal information. We encourage you to report any suspicious activity to info@dws.com, including any relevant documents and the original fraudulent email. Additionally, if you believe you have been a victim of fraud, please notify your local authorities and take steps to protect yourself.
Market Outlook - October 2026
09/10/2026

Vincenzo Vedda
Chief Investment Officer

Sabrina Reeh
Portfolio manager German Equities

Overview:
1. Market & Macro
Earnings momentum should continue to support equities despite high bond yields
“We remain positive on equities in the fourth quarter,” says Chief Investment Officer Vincenzo Vedda. He bases this optimistic assessment on two factors: the expected continued strength of corporate earnings and robust economic growth. Corporate earnings estimates are particularly noteworthy: for the first time in five years, 12-month earnings forecasts have been raised for every sector in the MSCI World.
The downside is that the scope for disappointment is high. If earnings momentum falls short of expectations, equity markets could come under pressure. Vedda identifies three further risk factors: first, high bond yields, which are increasing valuation pressure across many market segments. In the US, ten-year Treasury yields have risen above 5 percent, a level previously seen as critical for positive equity-market performance. The second, also familiar risk is the continued concentration of gains in the technology sector.
Around 50 percent of expected S&P 500 earnings growth for the third quarter of 2026 is projected to come from investment in artificial-intelligence infrastructure. Vedda sees the third risk in a potential slowdown in consumer spending amid high energy prices. “As long as the conflict between the US and Iran remains unresolved, there is unlikely to be an all-clear,” Vedda says. He identifies a third risk in the possibility that consumers may become less willing to spend amid high energy prices. “As long as the conflict between the US and Iran remains unresolved, there is unlikely to be an all-clear,” Vedda says.
Themes moving the capital markets
Economy: US and Germany deliver positive surprises
- Positive surprise: US gross domestic product growth for the second quarter was revised up from 1.5% to 2.2%. Consumer spending in particular proved more resilient than expected.
- Better than expected: the September ifo index, a monthly sentiment indicator for the German economy, shows that conditions in Germany are currently better than the public narrative suggests. The improvement is particularly pronounced in manufacturing.
Inflation: High energy prices keep inflation well above central-bank targets
- The US continues to face price increases well above the 2 percent inflation target. The current annualised inflation rate is 3.4 percent. However, price pressures appear to have eased somewhat recently.
- In Germany, higher energy prices pushed inflation up to 3.3 percent in September, from 2.9 percent in August.
Central banks: Further rate hikes are far from certain
- Recent US economic data support the view of a robust but not overheating US economy. The Federal Reserve is likely to remain cautious.
- In the Eurozone, the sharp rise in bond yields, which is already tightening financing conditions, makes an October rate hike unlikely in our view.
Risks: Further rise in bond yields
- A further increase in government-bond yields could put pressure on equity valuations, which have so far proved resilient to rising yields.
- France poses a particular risk, with sovereign bond spreads reaching new highs as fiscal consolidation appears increasingly remote.
2. Equities
German equities: Underappreciated opportunities from physical AI
What lies ahead for Germany’s benchmark Dax index? This year, it has been something of an international laggard. Nevertheless, portfolio manager Sabrina Reeh sees grounds for optimism. “In our view, the improvement in Germany’s leading economic indicators is more than a short-lived lift in sentiment. After several years of economic weakness, we are seeing initial signs of stabilisation.” Reeh points to the opportunities created by major public investment programmes. The full breadth of this spending has yet to feed through to the economy. “This suggests that we are closer to the beginning than the end of this investment cycle,” Reeh says. She therefore sees attractive opportunities within the German equity market to generate returns above the broader market through selective investment decisions. For the Dax as a whole, however, the global economic and investment cycle remains decisive.
Positive earningsmomentum
Earnings at Dax companies have recently developed much better than the negative sentiment would suggest. The German equity market is also far more broadly based than it was ten years ago. “Infrastructure, electrification, software, automation and industrial technology have become considerably more important,” Reeh says. The portfolio manager believes the Dax is much more exposed to technology and investment cycles than many investors may assume.
Huge potential fromphysical AI
Physical Artificial Intelligence (AI), in particular, could offer enormous potential. While many investors associate AI primarily with data centres or large language models, physical AI is about software, sensors, robotics and machinery performing real-world tasks. “Germany is home to many leading companies in automation, industrial software, sensor technology, drive systems and industrial equipment and has one of the highest robot densities in the world,” Reeh says. This makes the country not only an important supplier but also a natural adopter of these technologies. “The combination of industrial strength, labour shortages and a high degree of automation could make Germany one of the leading beneficiaries of physical AI,” Reeh says.
For German equities to perform well, however, the global economy must also play its part, as it has a greater influence than the domestic economy. “With a robust global investment cycle, many German companies should benefit disproportionately,” Reeh concludes.
German equities: Still lagging significantly
Equity performance year to date and in September 2026
Past performance is not a reliable indicator of future performance.
Sources: Bloomberg Finance L.P., DWS Investment GmbH, as of 30 September 2026.
US equities
Strong earnings growth should continue to support prices
|

German equities:
Signs of an economic recovery are mounting
|
European equities
Preference for European small and mid caps
|
Japan
Resilient economy benefits from AI investment
|
3. Bonds
US Treasuries look attractive after rise in yields
Following the recent rise in yields, we once again consider U.S. Treasuries more attractive. In our view, markets are pricing in more monetary tightening by the Federal Reserve than our economic outlook would suggest. At the same time, weaker growth and easing inflationary pressure could support US Treasury prices.
German Bunds considered a safe haven
The picture in Europe is more mixed. Concerns about French public finances have widened many countries’ spreads over German Bunds, while Bunds have benefited from their safe-haven status.
European IG bondsattractive
We also see attractive return opportunities in European investment-grade corporate bonds. Low price volatility, solid fundamentals and manageable new supply support the asset class, alongside attractive income and continued inflows. If interest-rate volatility subsides, demand could rise further.
European high-yield bonds also look more attractively valued following September’s correction, which widened spreads over government bonds by around 50 basis points; 100 basis points equal one percentage point. The improved economic and interest-rate outlook and continued solid demand are additional positives. Risks include global monetary tightening and rising new issuance.
U.S. Treasury yields have risen sharply
Yields have now also risen sharply in Japan
bp: basis points. 100 basis points equal one percentage point. Sources: Bloomberg Finance L.P., DWS Investment GmbH, as of 30 September 2026
US government bonds (10 years)
Attractive total returns
|
German government bonds (10 years)
Bunds in demand among investors
|
Emerging-market government bonds
Valuations no longer quite as attractive
|
Corporate bonds
Investment Grade
USA | Eurozone |
High Yield
USA | Eurozone |
4. Currencies
Euro/Dollar: Euro weakness likely to be temporary
|
5. Alternative investments
Gold: High bond yields weigh in the short term; prices should rise again over the long term
|
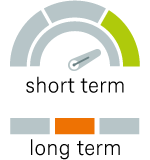
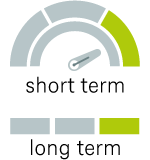
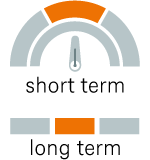
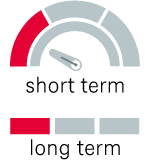
LegendThe strategic view by September 2027 The indicators signal whether DWS expects the asset class in question to develop upwards, sideways or downwards. They indicate both the short-term and the long-term expected earnings potential for investors. Source: DWS Investment GmbH; CIO Office, as of 09 October 2026 | |
 |
|
 |
|
 |
|
Forecasts are based on assumptions, estimates, views and hypothetical models or analyses which may prove to be incorrect. Past performance is not indicative of future results.